New-build or resale property in Cyprus and how to decide
New-build or resale property in Cyprus in 2026: VAT versus transfer fees, title deeds, buyer protection under the Specific Performance Law and the trade-offs.
Anyone buying a home in Cyprus soon faces a basic choice between a new property bought from a developer and a resale property bought from a private owner. The decision affects the taxes payable, the speed at which title passes, the level of legal protection during construction and, for investors, eligibility for the residence-by-investment route. As of October 2026 the trade-offs are clearer than they once were, partly because the 2026 tax reform abolished stamp duty and partly because buyer protections were strengthened in late 2023.
It is part of our property series, which begins with our guide to buying property in Cyprus as a non-EU national. The full list of charges is set out in our article on property taxes and costs.
Key takeaways
- New properties sold by developers are generally subject to VAT, while resales are generally subject to transfer fees.
- No transfer fees are payable when VAT has been paid on the purchase.
- Resale transfer fees are 3%, 5% and 8% on rising bands of value, reduced by 50%.
- A reduced 5% VAT rate can apply to a primary residence, subject to area and value limits.
- Contracts must be deposited with the Land Registry within six months to secure the buyer’s protection.
Tax on a new-build purchase
The first sale of a new building by a developer is normally subject to VAT at the standard rate of 19%. Buyers acquiring a primary and permanent residence may apply for the reduced rate of 5%. Under the regime introduced in June 2023, as confirmed by the Ministry of Finance in June 2026, the reduced rate applies to the first 130 m² of the property, with a value cap of €350,000, provided that the buildable area does not exceed 190 m² and the total value does not exceed €475,000. Transitional rules allowing the older 200 m² regime have been extended for qualifying applications until 31 December 2026.
When VAT has been paid, the Department of Lands and Surveys (DLS) charges no transfer fees on registering the property in the buyer’s name.
Tax on a resale purchase
A resale between private individuals is not usually subject to VAT. Instead, the buyer pays transfer fees when the title is registered. According to the DLS schedule of fees, these are charged on the sale price or market value:
- 3% on the portion up to €85,000;
- 5% on the portion between €85,000 and €170,000;
- 8% on the portion above €170,000.
A 50% reduction applies to these fees. On a resale of €300,000, for example, the gross fee would be €17,200 and the payable amount €8,600, before any other charges. The government’s online calculator does not apply the 50% reduction, so the result must be halved.
For buyers who also plan to apply for residence, our Cyprus residency page sets out how a qualifying purchase fits into the permit process.
Title deeds and timing
Resale properties often come with a separate title deed already issued, which allows the transfer to take place soon after completion. New-build units are commonly sold before title deeds are issued, and the transfer takes place once the development is completed and the deeds are issued, which can take time.
Protection under the Specific Performance Law
Where a property has no title deed yet, the buyer’s protection depends on depositing the contract of sale with the District Lands Office. Under the Sale of Immovable Property (Specific Performance) Law 81(I)/2011, as amended by Law 132(I)/2023, the contract must be deposited within six months of signing. Since 12 December 2023 the vendor must attach a search certificate dated within five working days, and buyers have new rights where a mortgage is registered on the land. Our Cyprus residency page explains how these rules interact with investment-based applications.
Recent price and transaction figures are summarised in our article on Cyprus property market trends.
Practical trade-offs
New-build homes typically offer modern energy performance, warranties, communal facilities and flexible payment schedules linked to construction stages. They may also be the more straightforward option for Cyprus permanent residence, where the main route is based on a first sale by a developer.
Resale homes are often in established neighbourhoods, with mature landscaping, larger plots and the possibility of inspecting exactly what is being bought. They may require renovation, and the condition of the building, outstanding planning matters and service charges need checking.
Due diligence points for both
- A search certificate from the DLS showing encumbrances and prohibitions.
- Confirmation of planning and building permits and, for older homes, the certificate of final approval.
- Clarity over who pays outstanding municipal charges and common expenses.
- For non-EU buyers, permission under the Acquisition of Immovable Property (Aliens) Law.
Buyers considering a purchase as part of a residence application should read our guide to Cyprus permanent residency by investment.
If you would like to talk through how these rules might apply to your own circumstances, our team would be glad to help. You can call +357 979 42 388 or write to us through our contact page.
Frequently asked questions
Do I pay both VAT and transfer fees?
No. When VAT has been paid on the purchase, no transfer fees are charged by the DLS.
Is stamp duty still payable on Cyprus property contracts?
Stamp duty was abolished from 1 January 2026. It remains relevant only for documents signed before that date.
Can a resale property qualify for Cyprus permanent residence?
Only in limited cases. The main route requires a first sale from a developer, with resales accepted mainly where the original contract was deposited before 7 May 2013.
Sources
- Department of Lands and Surveys, Rights and fees, as of October 2026.
- Department of Lands and Surveys, Contract of sale, consideration and exchange, as of October 2026.
- Ministry of Finance, Reduced 5% VAT rate on the purchase or construction of a residence, applications until 31 December 2026 (in Greek), 2026.
- gov.cy, Calculation of real estate transfer fees, as of October 2026.
- Tax Department, Tax Reform 2026, posted 29 May 2026.
This article is for general information only and does not constitute legal, tax or investment advice. Figures are stated as of 2026 and may change; confirm current requirements with the relevant authority and an independent adviser before acting. AT Express is a private consultancy and is not affiliated with any government or official programme.
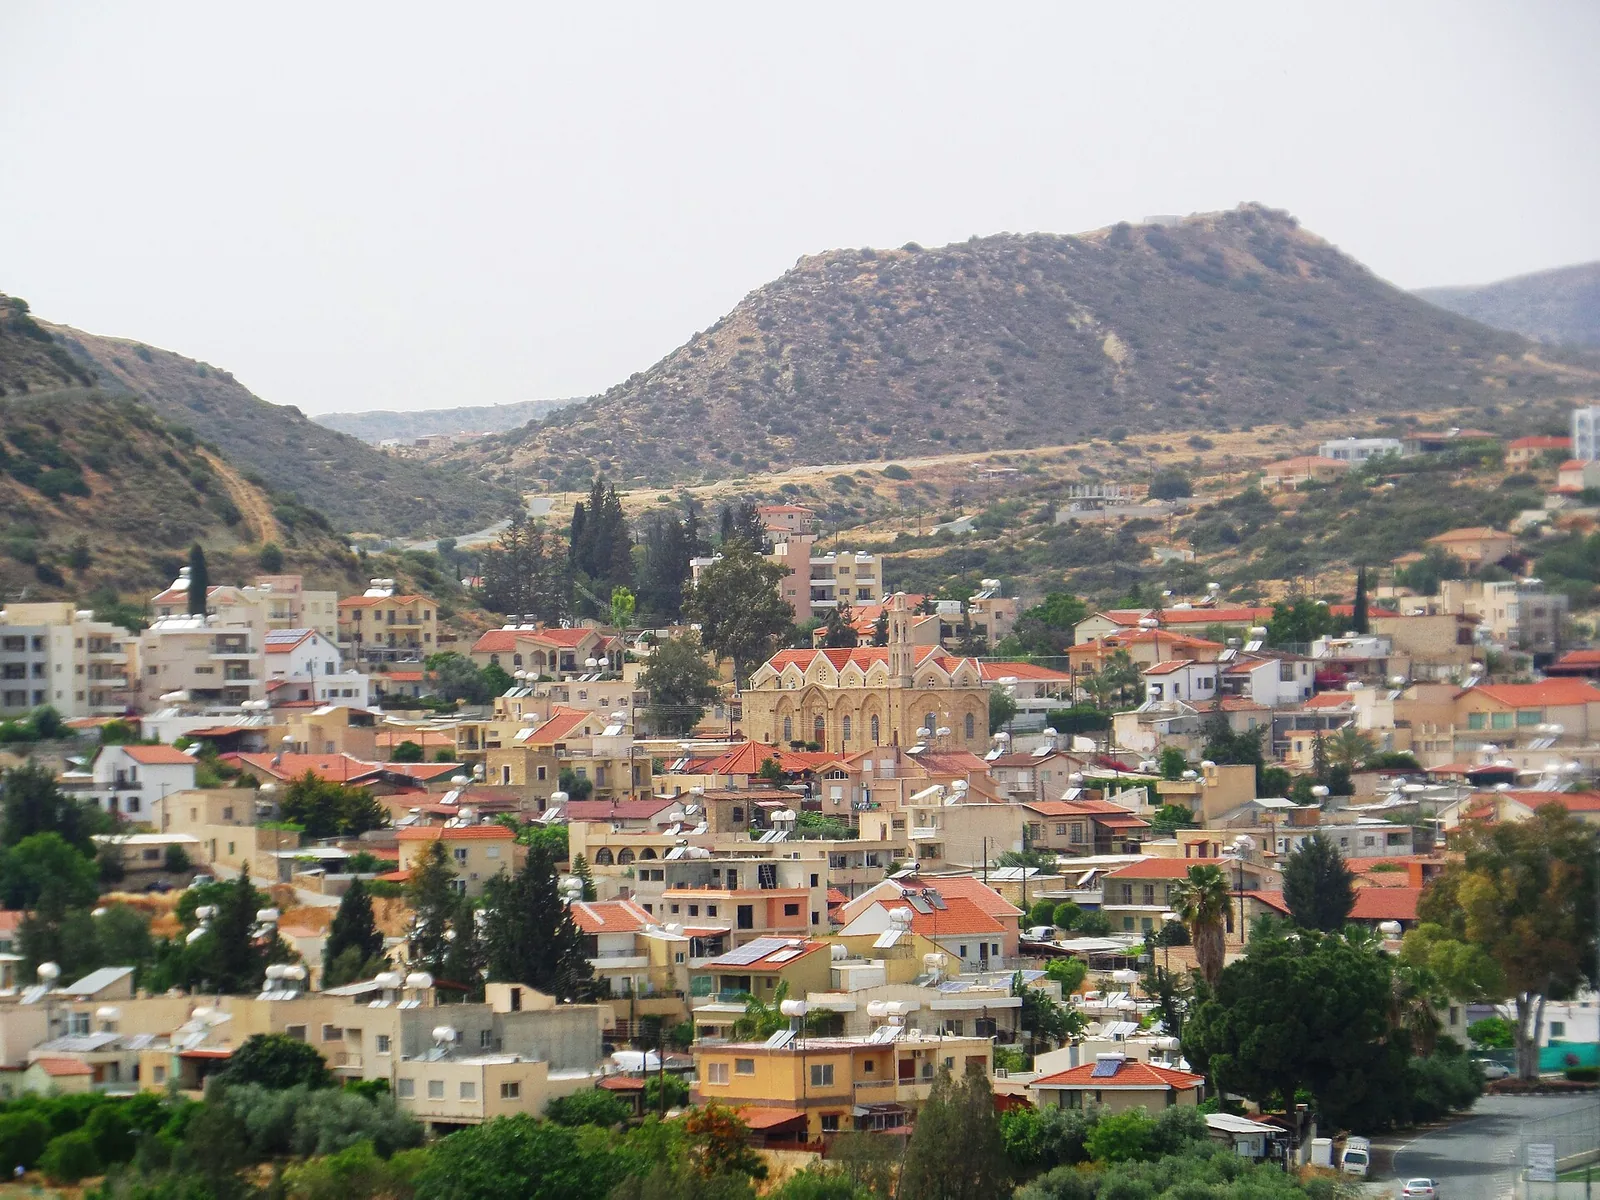
Featured image: “View of Germasogeia 10” by Xaris333, via Wikimedia Commons, CC BY-SA 4.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 30 October 2026 · Updated 31 October 2026