The EU list of non-cooperative jurisdictions in 2026
Which jurisdictions are on the EU list of non-cooperative jurisdictions after the October 2026 revision, what Annex II means and how listing affects owners.
Twice a year, the Council of the European Union reviews its list of non-cooperative jurisdictions for tax purposes. The list matters far beyond Brussels: it shapes how banks assess companies, how EU member states treat payments to certain jurisdictions and how investors choose where to structure their affairs.
AT Express is headquartered in Cyprus, with offices in the United Kingdom, Hong Kong, China, Vietnam and Singapore. We check the current list before recommending any jurisdiction, and this article summarises the position following the Council’s revision of 9 October 2026.
What the list is
The EU list was first adopted in 2017 as part of the EU’s external strategy for taxation. Jurisdictions are assessed against criteria on tax transparency, fair taxation and the implementation of international measures against base erosion and profit shifting. Those that fail to meet the criteria, and have not committed to address the shortcomings, are placed in Annex I, the list itself.
Annex II, sometimes called the grey list, is a state-of-play document. It records cooperative jurisdictions that have made commitments to reform but have not yet completed them. Appearing in Annex II is not a listing as non-cooperative, but it signals that the EU is monitoring the jurisdiction.
The position after 9 October 2026
Following the October 2026 revision, Annex I comprises:
- American Samoa, Anguilla, Guam, Palau, the Russian Federation, the Turks and Caicos Islands, the US Virgin Islands and Vanuatu.
Annex II includes the British Virgin Islands, Brunei Darussalam, Eswatini, Greenland, Jordan, Montenegro, Morocco, Panama, Türkiye and Viet Nam.
Several jurisdictions widely used for international companies, including the Cayman Islands, Hong Kong, the Seychelles, Singapore, the United Arab Emirates and the United States, appear in neither annex. The Council’s next revision is expected in February 2027, and the list can change at each review, so it should always be checked at source.
Our comparison of ten jurisdictions, including their current EU list position, is on our page on corporate services.
Why listing matters
Member states have agreed to apply defensive measures to Annex I jurisdictions. These can include denying tax deductions for payments to listed jurisdictions, applying stricter controlled foreign company rules, imposing withholding taxes and limiting participation exemptions on dividends. EU funding rules also restrict channelling funds through listed jurisdictions. Banks and other financial institutions frequently treat links to listed jurisdictions as a higher-risk factor under their anti-money-laundering procedures.
For an owner, a company in an Annex I jurisdiction can therefore mean higher tax costs in the EU, more demanding banking and closer scrutiny from counterparties. Our article on opening a bank account for an offshore company explains the banking side.
What Annex II means for BVI companies
The British Virgin Islands appear in Annex II, not Annex I. BVI companies are therefore not subject to the defensive measures that apply to listed jurisdictions, but owners should follow the BVI’s progress on its commitments at each review. Our BVI company formation page sets out the wider position, and our article comparing the BVI, Cayman and Seychelles explains the alternatives.
How jurisdictions move on and off the list
The list is not static. Jurisdictions are removed from Annex I once they have addressed the shortcomings identified, and moved into Annex II while commitments remain outstanding. Others are added when they fail to meet commitments or when the EU’s criteria are tightened. The Council’s Code of Conduct Group carries out the technical assessment, and the Council adopts each revision. For owners, this means that a jurisdiction’s status at the time a company is formed is no guarantee of its status in later years, and long-term structures should be reviewed as each revision is published.
It is also worth remembering that the EU list concerns tax cooperation. The EU maintains a separate list of high-risk third countries for anti-money-laundering purposes, which banks also take into account.
Practical steps for owners
- Check the current list before forming a company or opening an account, and again at each review.
- Review existing structures that involve Annex I jurisdictions with a licensed tax adviser.
- Consider how counterparties and banks will view the jurisdiction, not only how the law treats it.
- Remember that the list is one factor among several, alongside economic substance, CRS and FATCA reporting and the owner’s own residence.
Our pages on offshore company formation and international tax planning explain how we take the list into account when advising on structure.
If you would like to talk through how this applies to your own plans, our team would be glad to help. You can call +357 979 42 388, message us on WhatsApp or write to us through our contact page.
Sources
- Council of the European Union: Taxation: Council updates the EU list of non-cooperative jurisdictions for tax purposes (9 October 2026)
- Council of the European Union: EU list of non-cooperative jurisdictions for tax purposes
- European Commission: EU list of third-country jurisdictions for tax purposes
- OECD: Global Forum on Transparency and Exchange of Information for Tax Purposes
This article is for general information only and does not constitute legal, tax or financial advice. Company formations and bank accounts are subject to know-your-customer (KYC) and anti-money-laundering (AML) checks, and no outcome or timescale can be promised. Companies may be subject to economic substance rules, and accounts and their owners may be reported to tax authorities under the OECD Common Reporting Standard (CRS) and FATCA. Check the current EU list of non-cooperative jurisdictions for tax purposes and take independent advice in each country concerned. Figures are stated as at October 2026 and may change. AT Express is a private consultancy and is not affiliated with any government, registry or bank.
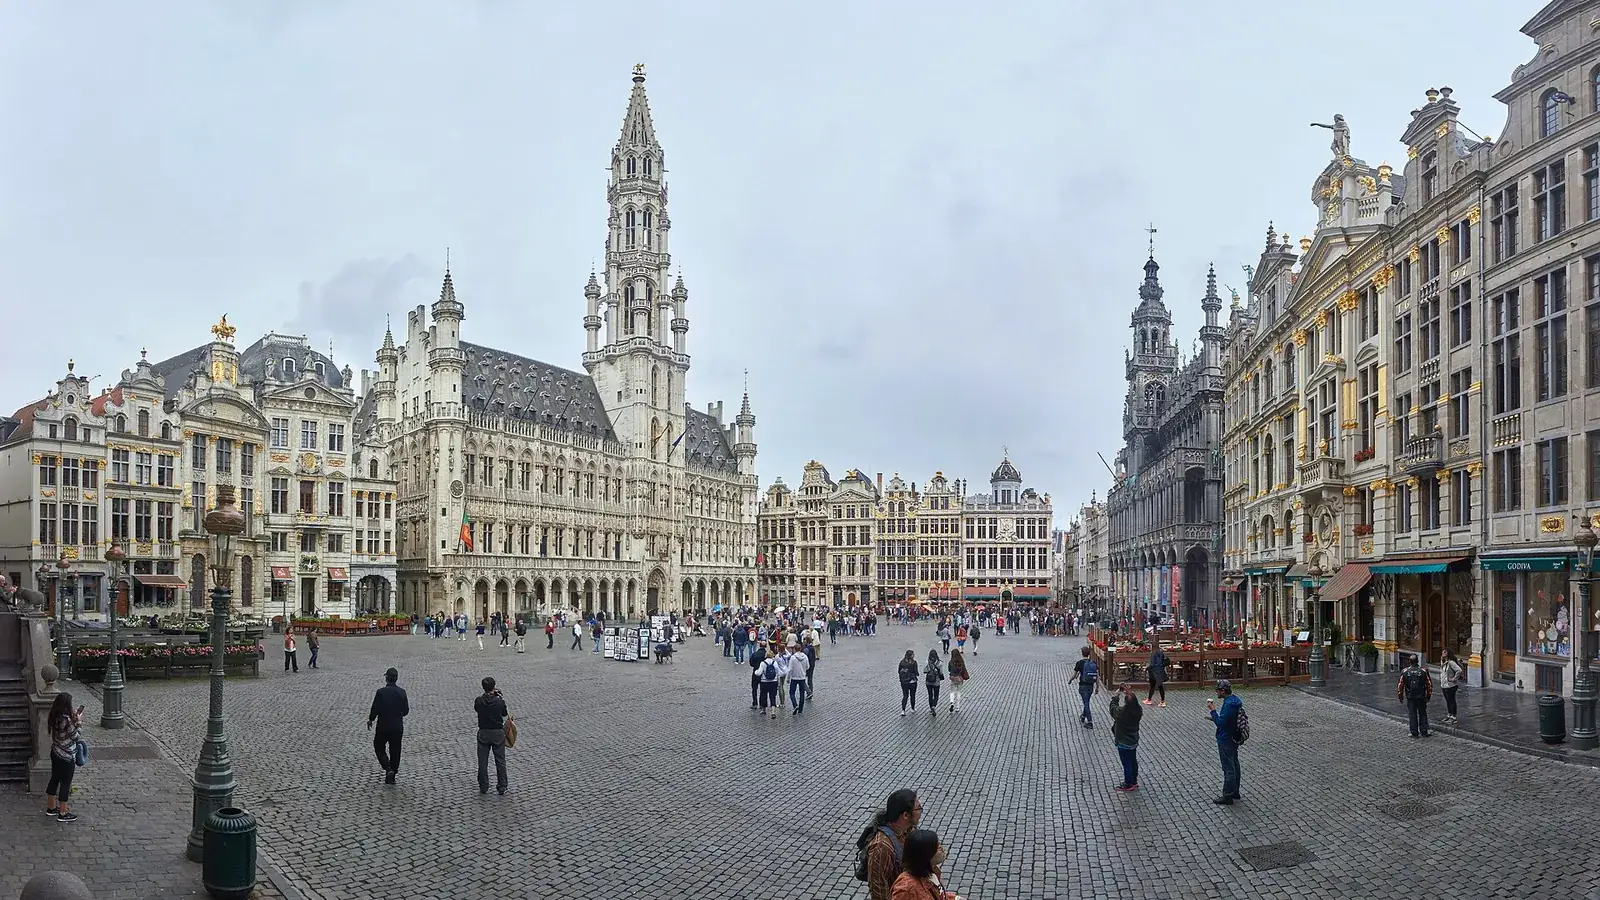
Featured image: “Grand-Place, Brussels – panorama, June 2018” by Celuici, licensed under CC BY-SA 4.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 31 October 2026 · Updated 31 October 2026