A UK limited company for non-residents in 2026
Forming a UK limited company from abroad: the £100 online fee, identity verification, directors, the public register, corporation tax from 19% to 25%, banking.
A UK private limited company remains one of the most respected corporate vehicles in the world. It can be formed online in a day, it is familiar to banks and customers everywhere, and it carries the credibility of a transparent public register. There is no requirement for the owners or directors to live in the United Kingdom.
AT Express is headquartered in Cyprus, with offices in the United Kingdom, Hong Kong, China, Vietnam and Singapore. Our London presence means we work with UK companies daily, and this guide sets out what non-resident owners should know.
Formation
According to GOV.UK, an application to register a company online costs £100 and is usually processed within 24 hours. The company needs:
- a name that is not the same as, or too like, an existing one;
- a registered office address in the United Kingdom, where official letters are sent and which appears on the public register;
- at least one director who is a natural person, who may live anywhere;
- at least one shareholder, and details of people with significant control; and
- articles of association, usually the standard model articles.
Identity verification
Companies House now requires directors and people with significant control to verify their identity. Verification can be completed directly with Companies House or through an authorised corporate service provider. Non-resident owners should allow time for this step, which applies to new and existing companies.
The public register
The UK register is public. Anyone can see a company’s directors, its people with significant control, its registered office, its filed accounts and its filing history. Home addresses are protected, as directors provide a separate service address, but names, months and years of birth and nationalities are visible. For owners who value privacy above all, this is a material consideration; for those whose customers want to verify them, it is an advantage.
The documents we ask for, and the services we provide afterwards, are set out on our page on UK company formation.
Corporation tax
GOV.UK publishes the current rates: a small profits rate of 19% for profits up to £50,000, a main rate of 25% for profits above £250,000, and marginal relief between the two. A UK company registers for corporation tax, files an annual company tax return with HM Revenue and Customs and pays the tax due. VAT registration is required once taxable turnover exceeds the registration threshold, and may be worthwhile voluntarily for some businesses.
Where the directors manage the company from another country, that country may also regard the company as resident there. The interaction between UK tax and the owners’ home tax rules should be checked with an adviser, and our page on international tax planning explains how we coordinate that work.
Annual obligations
- A confirmation statement to Companies House at least once a year.
- Annual accounts filed with Companies House, with an audit only where the company does not qualify for an exemption.
- A company tax return to HMRC each year.
- Updates to the register when directors, shareholders or people with significant control change.
Running the company from abroad
Many non-resident owners appoint a UK corporate service provider to provide the registered office, receive official mail and keep the statutory registers in order, and an accountant to prepare the accounts and tax return. Deadlines are strict and penalties for late filing are automatic, so a clear annual calendar is essential. Where the company employs staff in the United Kingdom, it must also register as an employer and operate payroll. Owners should keep board decisions properly minuted, wherever the directors meet, as the place of management can affect the company’s tax position.
Banking
UK high-street banks often expect directors to have a UK connection, and many non-resident owners begin with a licensed electronic money institution for day-to-day payments, adding a bank relationship as the business develops. Every provider applies its own due diligence, and none can be promised. Our page on international bank account opening explains how we prepare applications.
Is a UK company right for you?
A UK company suits businesses that value credibility, sell to European or global customers, or want an English-law vehicle with a public track record. It is less suited to owners who require privacy or who will trade mainly in Asia, where Hong Kong or Singapore may fit better. For an EU base, Cyprus offers a 15% rate within the single market. Our article on offshore and onshore companies and the overview of onshore company formation explain the wider options, and our corporate services page compares ten jurisdictions side by side.
If you would like to talk through how this applies to your own plans, our team would be glad to help. You can call +357 979 42 388, message us on WhatsApp or write to us through our contact page.
Sources
- GOV.UK: Set up a private limited company: register your company
- GOV.UK: Verify your identity for Companies House
- GOV.UK: Corporation tax rates and allowances
- GOV.UK: Running a limited company
This article is for general information only and does not constitute legal, tax or financial advice. Company formations and bank accounts are subject to know-your-customer (KYC) and anti-money-laundering (AML) checks, and no outcome or timescale can be promised. Companies may be subject to economic substance rules, and accounts and their owners may be reported to tax authorities under the OECD Common Reporting Standard (CRS) and FATCA. Check the current EU list of non-cooperative jurisdictions for tax purposes and take independent advice in each country concerned. Figures are stated as at October 2026 and may change. AT Express is a private consultancy and is not affiliated with any government, registry or bank.
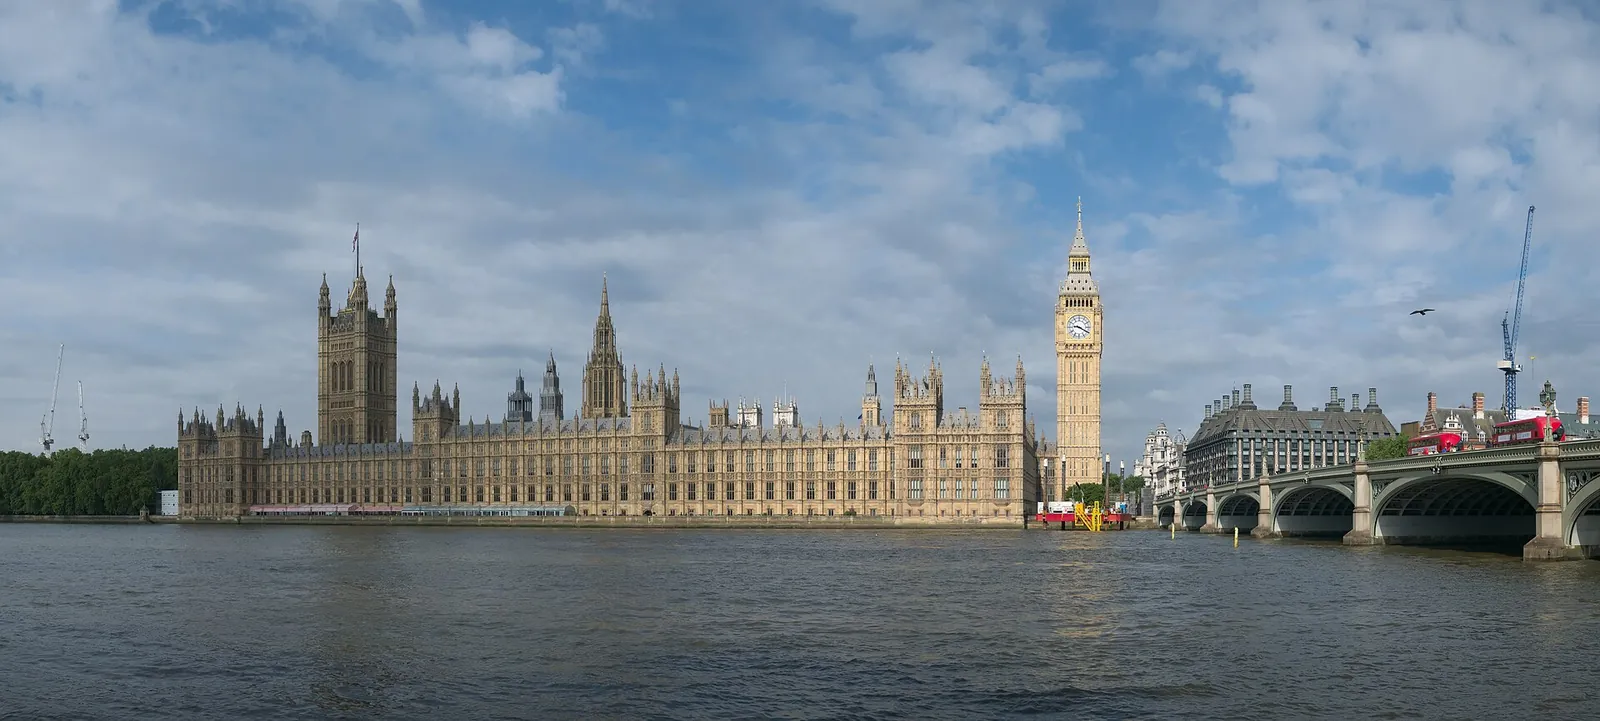
Featured image: “Palace of Westminster and Elizabeth Tower 20250522” by Domob, licensed under CC BY-SA 4.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 31 October 2026 · Updated 31 October 2026