Setting up a Singapore private limited company: resident director, secretary, 17% corporate tax with exemptions, ACRA filings, audit and banking, with sources.
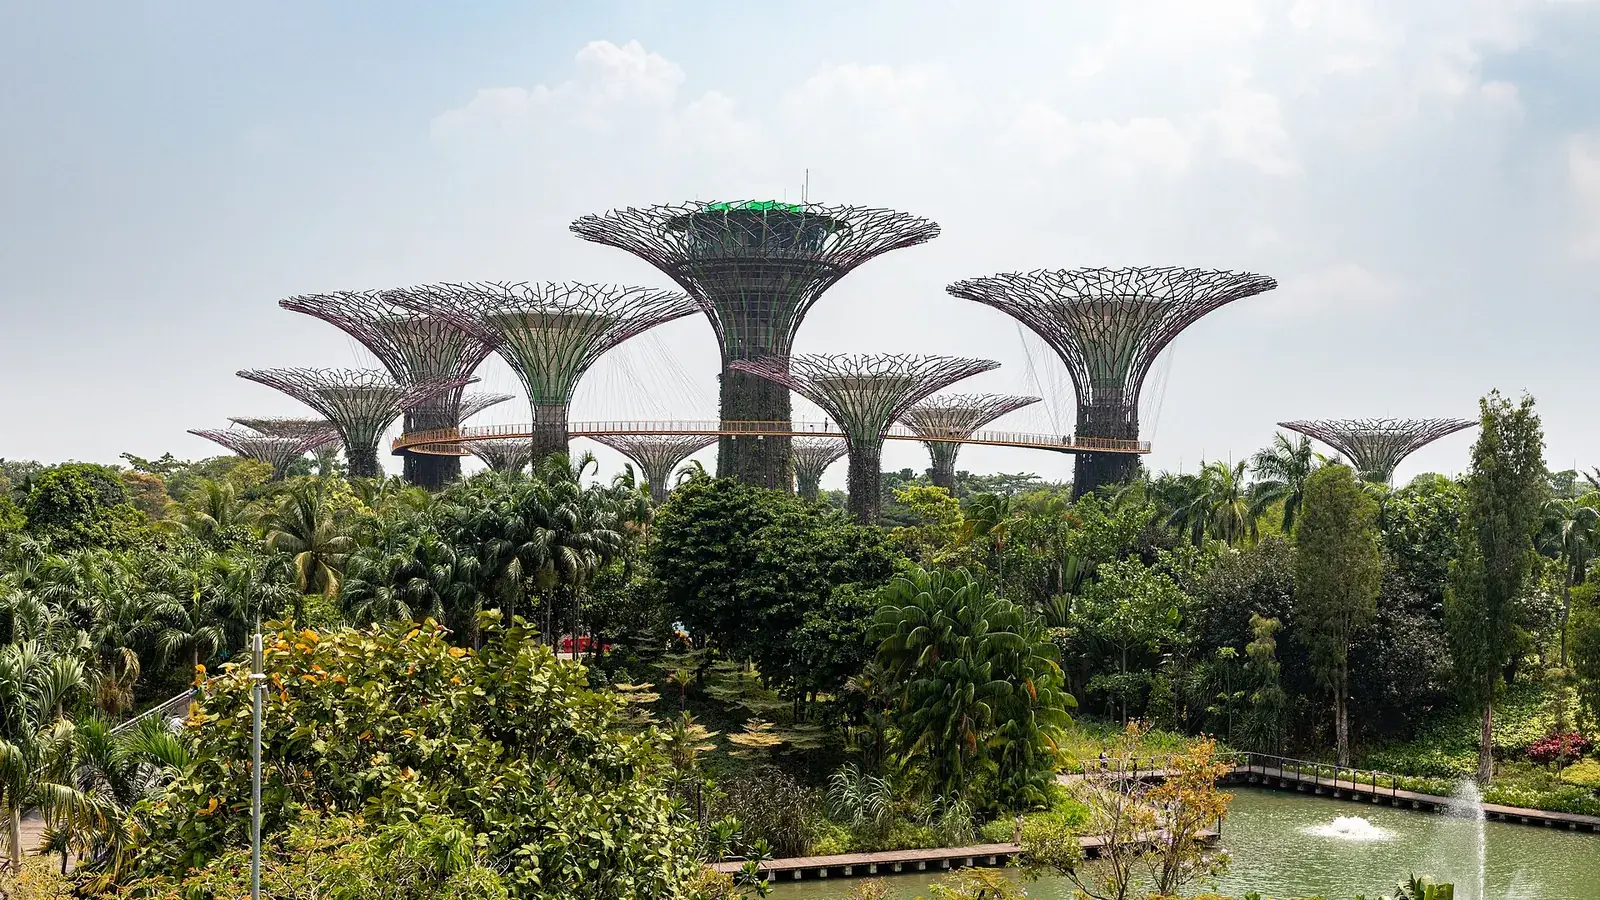
Supertree Grove at Gardens by the Bay in Singapore
Singapore · Private limited company

Singapore company formation.

A Singapore private limited company combines a highly regarded legal and regulatory environment with a competitive corporate tax system, making it a natural regional headquarters for Asia.

17%Headline corporate tax rate
OneLocally resident director
Six monthsTo appoint a secretary
BizfileOnline registration
Overview

A regional headquarters for Asia.

Singapore is consistently chosen by international groups for its stability, transparent regulation and connections across Southeast Asia.

Companies are registered with the Accounting and Corporate Regulatory Authority, ACRA, under the Companies Act 1967, through its online Bizfile service. Corporate income tax is administered by the Inland Revenue Authority of Singapore, IRAS. A Singapore company is an onshore entity with real compliance obligations, and it is valued precisely because counterparties, banks and regulators regard it highly.

AT Express is headquartered in Cyprus, with offices in the United Kingdom, Hong Kong, China, Vietnam and Singapore. Our Singapore office coordinates incorporation, corporate secretarial support and banking introductions with licensed local providers.

Company type

The private company limited by shares.

The private limited company, identified by “Pte. Ltd.” in its name, is the standard choice for owners who intend to trade, invoice or hold regional investments from Singapore. It may have up to fifty shareholders. Foreign companies can alternatively register a branch, but a subsidiary is usually more practical for banking, tax and liability purposes.

Key features

What sets Singapore apart.

  • One shareholder, individual or corporate, of any nationality.
  • At least one director ordinarily resident in Singapore, such as a citizen, permanent resident or qualifying pass holder.
  • A company secretary appointed within six months of incorporation, who cannot be the sole director.
  • A Singapore registered office open to the public during prescribed hours.
  • An extensive tax treaty network and a respected regulatory regime.
Private consultation

Planning a Singapore company?

We can explain the resident director requirement, the tax position and the banking route, and set out our fees in writing.

Tax policy

Competitive and transparent.

IRAS applies a flat corporate income tax rate of 17% to chargeable income, for local and foreign companies alike. Under the partial tax exemption scheme, 75% of the first S$10,000 and 50% of the next S$190,000 of normal chargeable income are exempt, and qualifying new start-up companies may claim a separate exemption instead. Singapore does not tax dividends paid by companies to shareholders under its one-tier system.

Foreign-sourced income received in Singapore can be taxable, subject to specific exemptions. Owners remain taxable in their own countries, where controlled foreign company rules may apply.

Independent advice. Rebates, exemptions and incentives change regularly. We arrange advice from licensed tax practitioners; see international tax planning.
Pros and cons

A balanced view.

+

Advantages

  • Exceptional reputation with banks, investors and trading partners.
  • Competitive corporate tax with partial exemptions.
  • Efficient online administration in English.
  • A natural base for operations across Southeast Asia.
−

Considerations

  • A locally resident director is mandatory, which non-resident owners must arrange.
  • Annual filings with ACRA and IRAS, and an audit unless the company qualifies for exemption.
  • Higher running costs than many offshore jurisdictions.
  • Banks expect genuine business links with Singapore or the region.
Requirements

What you will need.

  • At least one shareholder and at least one director ordinarily resident in Singapore.
  • A company secretary within six months of incorporation.
  • A registered office address in Singapore.
  • An approved company name and a constitution.
  • Identification and address documents for officers, shareholders and registrable controllers.
Process and timeline

From first call to registration.

01

Structure review

We confirm that Singapore suits your activity, staffing and tax position.

02

Name and officers

The name is reserved and the resident director and secretary arranged.

03

Registration

The application is filed through Bizfile with ACRA.

04

Tax and registers

Registers, including the register of registrable controllers, are prepared.

05

After formation

Banking applications and, where needed, GST and employment registrations follow.

Registration is quick once the name is approved and the officers are in place. Arranging a resident director and completing bank due diligence usually take longer; we confirm a realistic timetable in writing.

Ongoing compliance

Keeping the company in good standing.

  • Annual general meeting, unless dispensed with, and an annual return filed with ACRA.
  • Financial statements prepared each year, and audited unless the company qualifies as a small company exempt from audit.
  • Corporate income tax returns, including the estimated chargeable income where required, filed with IRAS.
  • Registers of members, directors and registrable controllers maintained and kept up to date.
  • Changes of officers notified to ACRA within the statutory period.
Bank accounts

Banking for a Singapore company.

Singapore companies can bank with local and international banks or licensed digital banks and payment institutions. Banks look for a credible business plan, substance in Singapore or the region and full information on the owners. Approval is at the bank’s discretion. See international bank account opening and our comparison of Hong Kong and Singapore companies.

Questions

Frequently asked questions.

Can a foreigner own 100% of a Singapore company?
Yes. Shareholders may be of any nationality. At least one director must, however, be ordinarily resident in Singapore.
What is the corporate tax rate in Singapore?
IRAS applies a flat rate of 17% to chargeable income, with partial exemptions on the first S$200,000 of normal chargeable income and a separate scheme for qualifying start-ups.
When must a company secretary be appointed?
Within six months of incorporation. The secretary must be a natural person resident in Singapore and cannot be the sole director.
Is an audit always required?
No. Companies that qualify as small companies under the Companies Act may be exempt from audit, although they must still prepare financial statements.
Is Singapore better than Hong Kong?
Neither is better in general. The right choice depends on your markets, staff, banking and tax position, which our comparison of the two explains.
Sources

Official sources.

  1. Accounting and Corporate Regulatory Authority, Choosing company directors and other key officers — resident director and secretary requirements.
  2. Accounting and Corporate Regulatory Authority, Post-registration guide: local company.
  3. Inland Revenue Authority of Singapore, Corporate income tax rate, rebates and tax exemption schemes.
  4. Council of the European Union, EU list of non-cooperative jurisdictions for tax purposes.
  5. OECD, International standards on tax transparency, including the Common Reporting Standard.
  6. Internal Revenue Service, Foreign Account Tax Compliance Act (FATCA).

Hero image: “Singapore (SG), Gardens by the Bay, Supertree Grove — 2019 — 4752” by Dietmar Rabich, licensed under CC BY-SA 4.0.

Please note. This page is a general summary for information only and does not constitute legal, tax or financial advice. Every company formation and bank account is subject to know-your-customer (KYC) and anti-money-laundering (AML) checks by the registered agent, registry and bank, and no outcome or timescale can be promised. Companies may be subject to economic substance rules, and their accounts and owners may be reported to tax authorities under the OECD Common Reporting Standard (CRS) and the US Foreign Account Tax Compliance Act (FATCA). Check whether any jurisdiction involved appears on the EU list of non-cooperative jurisdictions for tax purposes, and take independent tax and legal advice in each country concerned. AT Express works with licensed corporate service providers, lawyers and accountants and is not affiliated with any government, registry or bank. Last reviewed: 30 October 2026.
How we work

Four calm steps.

A simple, transparent process. The scope of our work and our fees are set out in writing before anything begins.

  1. 01

    A first conversation

    We discuss what the company will do, who will own and run it, and where its customers and people are.

  2. 02

    A written proposal

    We compare suitable jurisdictions and set out the documents, timetable and fees, so you can decide calmly.

  3. 03

    Formation and banking

    We coordinate due diligence, incorporation and bank applications with licensed providers in each jurisdiction.

  4. 04

    Ongoing compliance

    We keep track of renewals, filings and reporting each year and remain your single point of contact.

Begin with a conversationConfidential and without obligation
From our insights

Further reading

All insights
Aphrodite's Rock on the coast near Paphos, Cyprus
Let's talk

Begin with a conversation.

Tell us a little about your plans. An adviser will reply personally with an initial view of the options available to you — confidentially and without obligation.

Arrange a consultation

Prefer to talk first? Message us on WhatsApp
  • One dedicated adviser
  • Scope and fees in writing
  • Confidential, without obligation