UAE free zone companies and corporate tax: a practical guide
How UAE corporate tax applies to free zone companies: the 9% rate, the 0% regime for qualifying free zone persons, its conditions, audits and registration.
For many years the United Arab Emirates were known for having no corporate tax at all. That changed with the federal corporate tax law, which applies to financial years starting on or after 1 June 2023. Free zones remain attractive, but the rules now reward companies with genuine operations and careful record-keeping, and penalise those that assume the old position still holds.
AT Express is headquartered in Cyprus, with offices in the United Kingdom, Hong Kong, China, Vietnam and Singapore. We coordinate UAE formations with licensed local providers, and this guide sets out the main points for owners considering a free zone company.
The basic rates
According to the Federal Tax Authority, taxable income up to AED 375,000 is taxed at 0%, and taxable income above that threshold at 9%. These rates apply to mainland companies and to free zone companies that do not qualify for special treatment.
Every taxable person, including free zone companies, must register for corporate tax and file an annual return, even where no tax is ultimately payable. Registration and filing are handled through the Federal Tax Authority’s online platform.
The qualifying free zone person
A free zone company that meets a set of conditions is treated as a qualifying free zone person. It pays 0% on its qualifying income and 9% on other taxable income. The conditions, as summarised by the Federal Tax Authority, are that the company:
- maintains adequate substance in the UAE, with sufficient assets, staff and operating expenditure for its activities;
- derives qualifying income, which depends on the type of activity and, in many cases, on whether the counterparty is itself in a free zone;
- complies with the transfer pricing rules and keeps the related documentation;
- prepares audited financial statements;
- has not elected to be taxed at the standard rates; and
- keeps its non-qualifying revenue within the de minimis limit, which is the lower of AED 5 million or 5% of total revenue.
Failing any condition removes the 0% treatment, not only for the period concerned but for the following four tax periods as well. This is the most important practical point for owners: the 0% regime is valuable, but it requires discipline every year.
We explain the differences between mainland and free zone licences, and the documents involved, on our page on UAE company formation.
Free zone or mainland?
The choice depends mainly on where the customers are. A free zone company is well suited to international trade, services delivered outside the UAE and dealings with other free zone businesses. A mainland company can trade freely within the UAE market; permitted activities and ownership requirements depend on the licensing authority concerned.
Where most revenue will come from customers on the UAE mainland, the qualifying-income test may be difficult to meet, and a mainland company, taxed at the standard rates, may be simpler and more transparent. Each licensing authority sets its own requirements and fees, so the comparison is specific to the activity.
Substance, banking and reputation
UAE banks apply thorough due diligence, and a company with a real office, staff and local customers is far easier to bank than one without. Our page on international bank account opening explains how we prepare applications, without any promise of approval.
The UAE is a cooperative jurisdiction under the EU list following the Council’s October 2026 revision, as our article on the EU list in 2026 explains. It exchanges financial account information under the Common Reporting Standard, so accounts held by UAE companies, and the individuals who control them, are reported to tax authorities. Our article on CRS and FATCA reporting explains what that means for owners.
The owner’s own tax position
A low rate in the UAE does not settle the owner’s position at home. Many countries tax residents on the profits of foreign companies they control, and a company managed from abroad may be treated as resident there. Our page on international tax planning describes how we coordinate advice with licensed advisers in each country involved, and our article on economic substance explains why genuine activity matters across low-tax jurisdictions.
A sensible checklist
- Decide where the customers are, and whether qualifying income is realistic.
- Choose a free zone whose permitted activities match the business.
- Plan for real substance: premises, people and decision-making in the UAE.
- Budget for annual audited financial statements and transfer pricing documentation.
- Register for corporate tax promptly and diarise the annual return.
For a wider view of how the UAE compares with Hong Kong, Singapore, the United Kingdom and Cyprus, see our overview of onshore company formation and the comparison table on our corporate services page.
If you would like to talk through how this applies to your own plans, our team would be glad to help. You can call +357 979 42 388, message us on WhatsApp or write to us through our contact page.
Sources
- Federal Tax Authority: Corporate Tax general guide
- Federal Tax Authority: Corporate tax
- Federal Tax Authority: Basic tax information: free zone persons
- European Commission: EU list of third-country jurisdictions for tax purposes
- OECD: Global Forum on Transparency and Exchange of Information for Tax Purposes
This article is for general information only and does not constitute legal, tax or financial advice. Company formations and bank accounts are subject to know-your-customer (KYC) and anti-money-laundering (AML) checks, and no outcome or timescale can be promised. Companies may be subject to economic substance rules, and accounts and their owners may be reported to tax authorities under the OECD Common Reporting Standard (CRS) and FATCA. Check the current EU list of non-cooperative jurisdictions for tax purposes and take independent advice in each country concerned. Figures are stated as at October 2026 and may change. AT Express is a private consultancy and is not affiliated with any government, registry or bank.
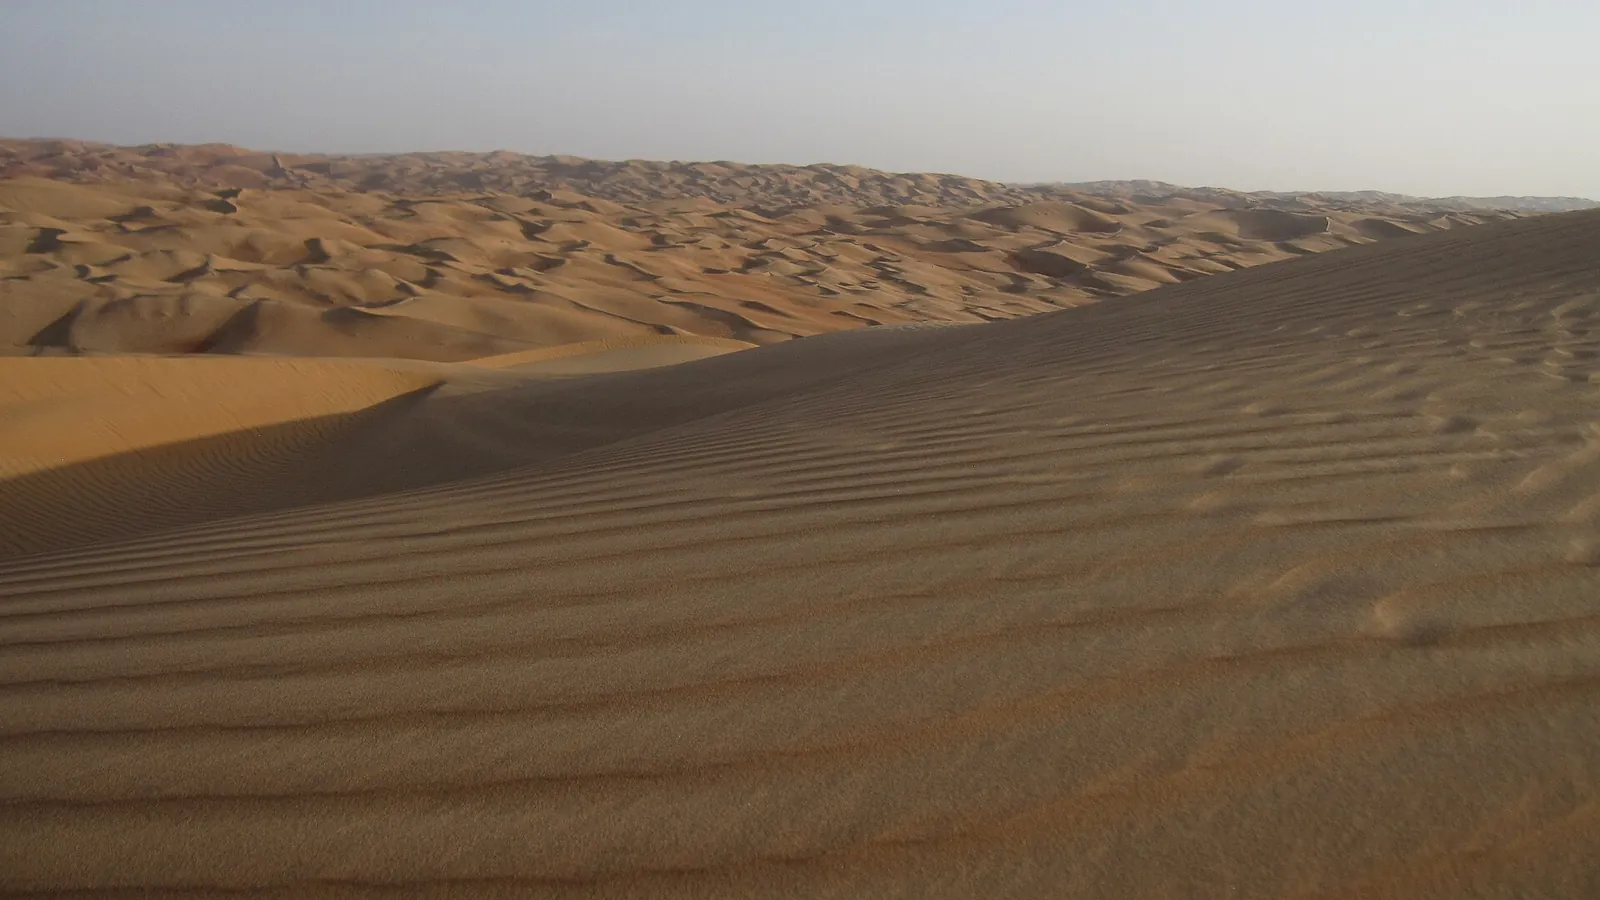
Featured image: “Liwa Desert” by Jc8136, licensed under CC BY-SA 3.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 31 October 2026 · Updated 31 October 2026