Opening a corporate bank account in Cyprus in 2026
What Cyprus banks ask for when opening a corporate account in 2026: due diligence, beneficial ownership, substance, source of funds and deposit protection.
For most new Cyprus companies, opening a bank account is the step that takes longest. Incorporation can be completed in days, but banks must satisfy themselves about who owns and controls the company, where its money comes from and what it will do. Since the reforms that followed the 2013 banking crisis and the tightening of European anti-money laundering rules, Cyprus banks have become markedly more selective. As of October 2026 the process is predictable for well-prepared applicants, but it rewards clarity and documentation far more than speed.
A bank account usually follows incorporation, covered in our guide on how to set up a company in Cyprus, and banks will ask for evidence of the beneficial owners recorded under our article on the beneficial ownership register.
Key takeaways
- Banks apply customer due diligence under EU and Cyprus anti-money laundering law.
- Every ultimate beneficial owner must be identified and verified.
- A credible business plan and evidence of source of funds and wealth are central to approval.
- Substance in Cyprus, such as an office, local director or staff, often helps.
- Eligible deposits are protected up to €100,000 per depositor per bank under EU rules.
Why banks ask so many questions
Cyprus credit institutions are supervised by the Central Bank of Cyprus, and the largest fall under direct European Central Bank supervision through the Single Supervisory Mechanism. They are required to apply customer due diligence measures before establishing a business relationship, to understand the purpose of the account and to monitor transactions throughout the relationship.
The practical effect is that the bank’s decision depends less on the company itself and more on the people and activities behind it. Complex ownership chains, high-risk jurisdictions or unclear business models lengthen the review or lead to refusal.
The documents usually requested
Requirements vary between banks, but most corporate account applications include:
- the certificate of incorporation, memorandum and articles, and certificates of directors, secretary, shareholders and registered office;
- certified passports and proof of address for directors, shareholders and ultimate beneficial owners;
- a description of the business, expected turnover, main counterparties and countries of operation;
- evidence of source of funds and source of wealth for the beneficial owners;
- contracts, invoices or letters of intent supporting the planned activity;
- for holding structures, organisational charts showing each layer of ownership.
Documents issued abroad generally need to be apostilled or legalised, and those not in English or Greek translated.
The interview
Most banks hold an interview with the beneficial owners and directors, in person or by video. The aim is to confirm that the people involved understand the business and that the stated activity is genuine. Applicants who can explain their business clearly and consistently tend to move through this stage quickly.
For a structured overview of the process, our bank account opening page sets out how we prepare the file and the introduction to the bank.
Substance and why it matters
Banks pay close attention to whether a company has a real presence in Cyprus. A local registered office, a resident director with real authority, staff or a commercial lease can support the application, particularly for trading and service companies. A company with no connection to Cyprus beyond its registration is more likely to be questioned.
Substance also matters for tax purposes, for treaty access and for how other jurisdictions treat payments to the company. Our bank account opening page outlines how applications are typically prepared.
The rules on using a serviced address are explained in our article on registered and virtual offices.
Keeping the account in good standing
Approval is not the end of due diligence. Banks review accounts periodically and may ask for updated documents, explanations of unusual transactions or evidence supporting large payments. Companies that keep their records up to date usually find these reviews straightforward.
- Notify the bank promptly of changes in directors, shareholders or beneficial owners.
- Keep invoices and contracts that match incoming and outgoing payments.
- File annual returns and financial statements on time, as banks often request them.
- Ensure that actual activity stays consistent with the profile declared at onboarding.
Tax filings that banks may ask to see are listed in our guide to corporate tax deadlines.
Alternatives and complements
Some companies combine a traditional bank account with an account at an electronic money institution or payment institution licensed in the EU. These can be quicker to open and suited to card payments or multi-currency transfers, but funds held there are safeguarded rather than covered by the deposit guarantee scheme, and some counterparties or authorities may prefer a bank account.
Deposit protection
Under Directive 2014/49/EU on deposit guarantee schemes, eligible deposits are protected up to €100,000 per depositor per credit institution. Cyprus applies this framework through its national deposit guarantee scheme. Companies holding larger balances often spread them across institutions or use other instruments, according to their treasury policy.
If you would like to talk through how these rules might apply to your own circumstances, our team would be glad to help. You can call +357 979 42 388 or write to us through our contact page.
Frequently asked questions
How long does it take to open a corporate account in Cyprus?
It depends on the bank and the complexity of the structure. Simple, well-documented applications move faster than multi-layered structures with owners in several countries.
Do directors need to travel to Cyprus?
Not always. Many banks accept video interviews and certified documents, although some prefer an in-person meeting for higher-risk profiles.
Is a Cyprus bank account guaranteed once the company is registered?
No. Each bank makes its own risk-based decision, and an application may be refused even when all documents are provided.
Sources
- European Union, Directive 2014/49/EU on deposit guarantee schemes.
- Central Bank of Cyprus, Licensing and supervision of banks, as of October 2026.
This article is for general information only and does not constitute legal, tax or investment advice. Figures are stated as of 2026 and may change; confirm current requirements with the relevant authority and an independent adviser before acting. AT Express is a private consultancy and is not affiliated with any government or official programme.
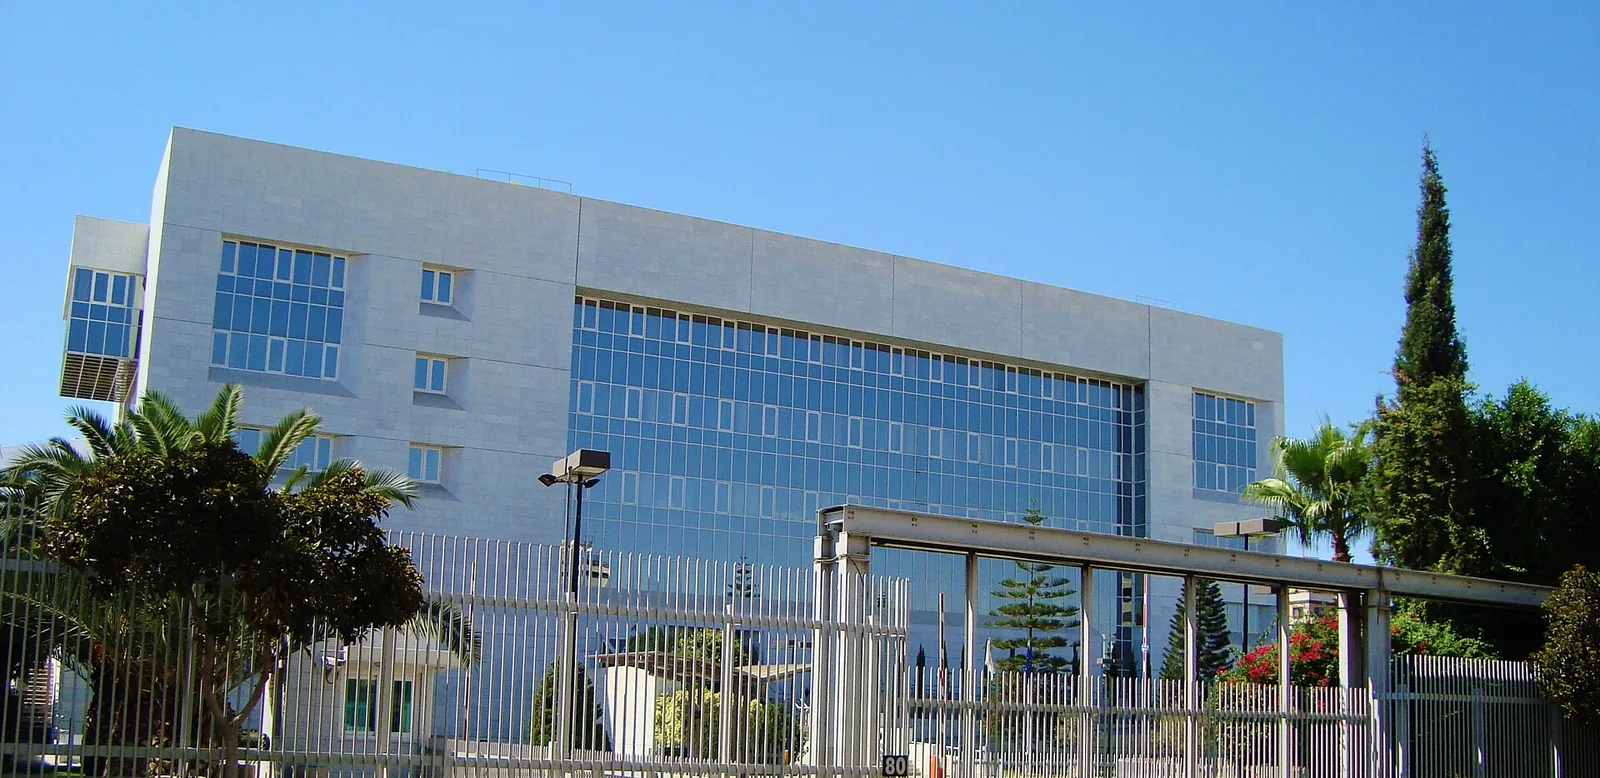
Featured image: “Cyprus central bank Nicosia Republic of Cyprus” by TourinNicosia, via Wikimedia Commons, CC BY-SA 3.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 30 October 2026 · Updated 31 October 2026