A Delaware LLC for non-residents: what owners should know
Forming a Delaware LLC from abroad: registered agent, the $400 annual tax, federal tax, Form 5472 for foreign owners, beneficial ownership rules and banking.
The United States is the largest consumer market in the world, and for many international entrepreneurs a US company is the natural way to reach it. Delaware has long been the state of choice, thanks to its well-developed company law and its specialist business courts. For non-resident owners, the limited liability company, or LLC, is usually the starting point.
AT Express is headquartered in Cyprus, with offices in the United Kingdom, Hong Kong, China, Vietnam and Singapore. We coordinate US formations with licensed registered agents, and this guide sets out what non-resident owners should know before they begin.
Why an LLC?
An LLC combines limited liability for its members with flexible management and, by default, simple tax treatment. A single-member LLC owned by a non-resident is generally treated by the Internal Revenue Service as a disregarded entity, meaning that it is not taxed as a separate company at federal level; instead, any US tax falls on the owner. A multi-member LLC is treated as a partnership by default. An LLC may also elect to be taxed as a corporation.
A Delaware corporation, by contrast, is a separate taxpayer subject to federal corporate income tax at 21%. Corporations are usually preferred where outside investors, share options or a future listing are in prospect.
Formation and the registered agent
Every Delaware company must maintain a registered agent with a physical address in the state. The agent files the certificate of formation, receives official documents and, in practice, is the company’s point of contact with the Division of Corporations. Owners need not visit the United States to form an LLC.
After formation, the company will usually need an Employer Identification Number from the IRS, which is required for tax filings and, in most cases, for opening a bank account.
Annual obligations
- Delaware annual tax. According to the Division of Corporations, every LLC pays an annual tax of $400, due on or before 1 June each year, regardless of its activity.
- Form 5472. The IRS requires a foreign-owned single-member LLC to file Form 5472, with a pro forma Form 1120, each year to report transactions with its owner and related parties. Failure to file can attract a penalty of $25,000.
- Federal and state tax. Where the LLC carries on business in the United States, the owner may have US tax to pay and returns to file. State taxes and registrations may also apply where the company trades in other states.
The documents we ask for, and the choice between an LLC and a corporation, are covered on our page on Delaware company formation.
Beneficial ownership reporting
The rules on reporting beneficial owners to the Financial Crimes Enforcement Network have changed since they were introduced. Under FinCEN’s current rule, companies created in the United States are exempt from beneficial ownership reporting, while the requirement applies to certain foreign companies registered to do business in the US. Because this area has moved quickly, we check FinCEN’s current guidance at the time of each formation.
Banking
Opening a US bank account for a non-resident-owned LLC can be demanding. Many banks expect the owner to attend in person, and all will want to understand the business and its source of funds. Licensed payment institutions offer an alternative for day-to-day receipts and payments. Our page on international bank account opening explains how we prepare applications, and our article on banking for offshore and international companies covers the wider picture.
Reporting and the owner’s home country
The United States is not part of the OECD Common Reporting Standard, but operates its own regime, FATCA, and exchanges information with many countries under intergovernmental agreements. Owners should assume that their home tax authority may learn of the company and its accounts, and many countries tax residents on the income of entities they control. Our article on CRS and FATCA reporting and our page on international tax planning explain the considerations.
Is a Delaware LLC right for you?
A Delaware LLC suits owners selling to US customers, holding US investments or working with US partners who expect a US counterparty. It is rarely the right choice simply to hold assets outside the United States or to trade with the rest of the world; for that, a company in the United Kingdom, Hong Kong or Cyprus may fit better. The comparison table on our corporate services page sets out the options side by side.
If you would like to talk through how this applies to your own plans, our team would be glad to help. You can call +357 979 42 388, message us on WhatsApp or write to us through our contact page.
Sources
- Delaware Division of Corporations: LLC, LP and GP tax instructions
- Internal Revenue Service: Limited liability company (LLC)
- Internal Revenue Service: About Form 5472
- Financial Crimes Enforcement Network: Beneficial ownership information reporting
- Internal Revenue Service: Foreign Account Tax Compliance Act (FATCA)
This article is for general information only and does not constitute legal, tax or financial advice. Company formations and bank accounts are subject to know-your-customer (KYC) and anti-money-laundering (AML) checks, and no outcome or timescale can be promised. Companies may be subject to economic substance rules, and accounts and their owners may be reported to tax authorities under the OECD Common Reporting Standard (CRS) and FATCA. Check the current EU list of non-cooperative jurisdictions for tax purposes and take independent advice in each country concerned. Figures are stated as at October 2026 and may change. AT Express is a private consultancy and is not affiliated with any government, registry or bank.
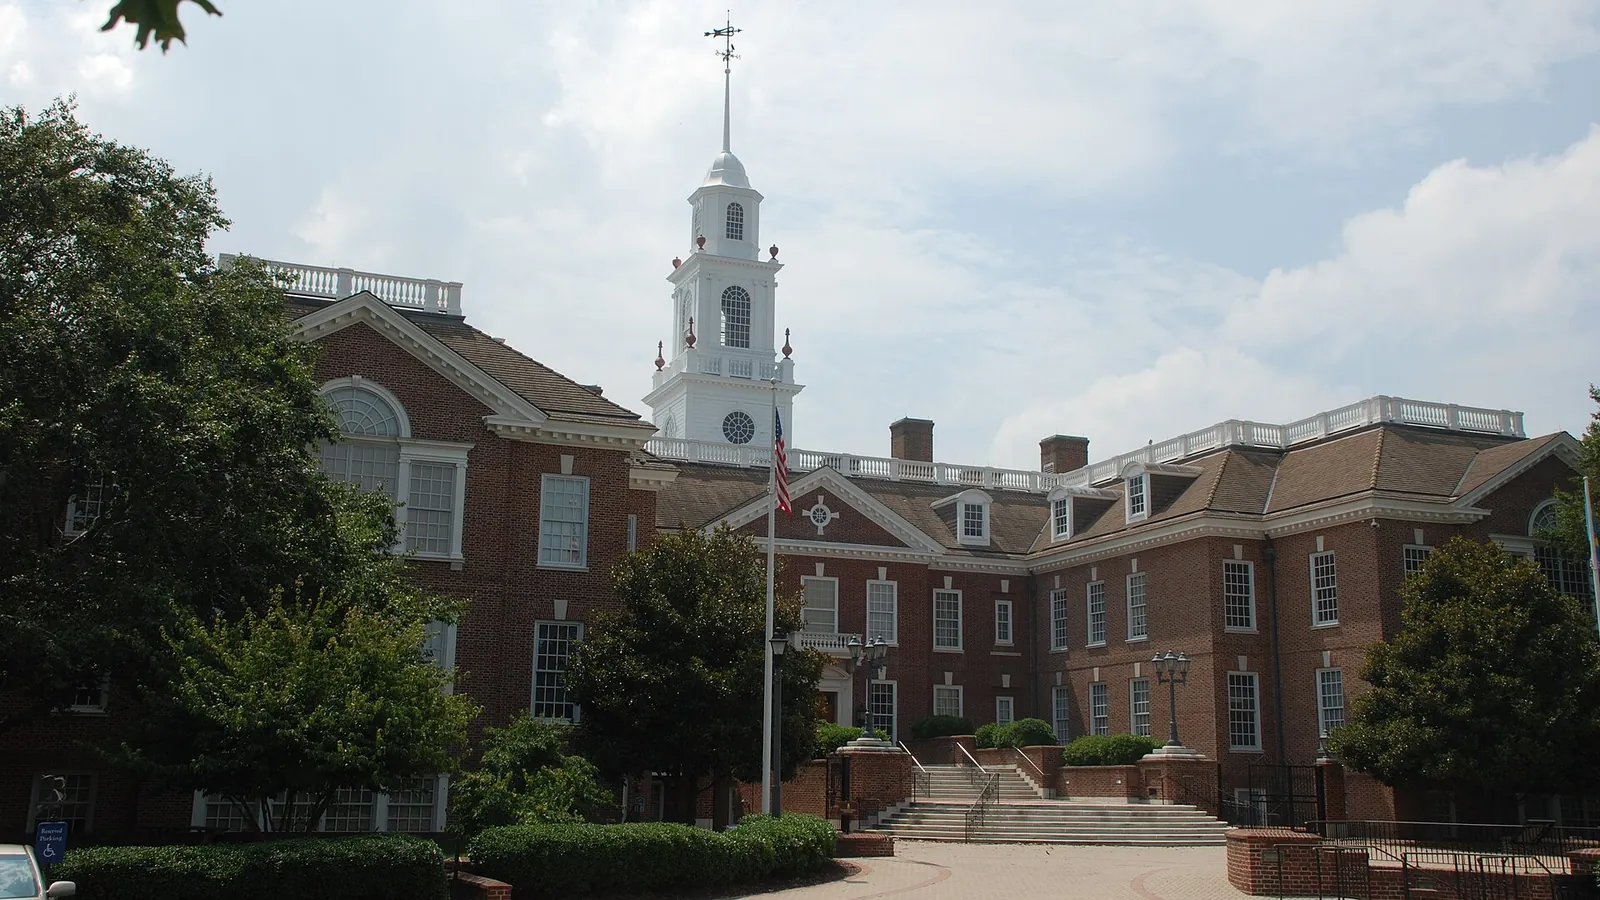
Featured image: “Delaware Legislative Hall Dover DSC 3463 ad (cropped)” by Adavyd, licensed under CC BY-SA 3.0.
Please note. This article is for general information only and reflects our understanding at the date of publication. Programme rules, thresholds and fees are set by each government and can change at short notice. It is not legal, tax or financial advice; please check the current position with us or the relevant authority before acting.
By the AT Express editorial team · Published 31 October 2026 · Updated 31 October 2026